Retirement & Longevity Strategy
Social Security Claiming Calculator
Analyze your Social Security retirement benefit across claiming ages 62 through 70. Compare early retirement reductions against 8% annual delayed credits and pinpoint your exact lifetime break-even age.
- Social Security Act Title II Statutory Math
- 100% Client-Side Private Modeling
- Exact Break-Even & Longevity Stress-Testing
Benefit & Longevity Parameters
Results
Optimal Claiming Age (For Age 85 Lifespan)
Claim at Age 70
Monthly Benefit: $2,480 / mo ($29,760 / yr)
- Cumulative Lifetime Total (to Age 85)
- $446,400
- Break-Even Age (vs. FRA 67)
- Age 82.5
Claiming Milestone Comparison (62 vs. 67 vs. 70)
Lifetime at 85: $386,400
Lifetime at 85: $432,000
Lifetime at 85: $446,400
Statutory Break-Even Thresholds
- Break-Even: Claiming at Age 62 vs. Full Retirement Age 67
- Age 78.7 (78 yrs, 8 mos)
- Break-Even: Claiming at FRA 67 vs. Delaying to Age 70
- Age 82.5 (82 yrs, 6 mos)
- Break-Even: Claiming at Age 62 vs. Delaying to Age 70
- Age 80.4 (80 yrs, 4 mos)
Monthly Benefit Scale Across Ages
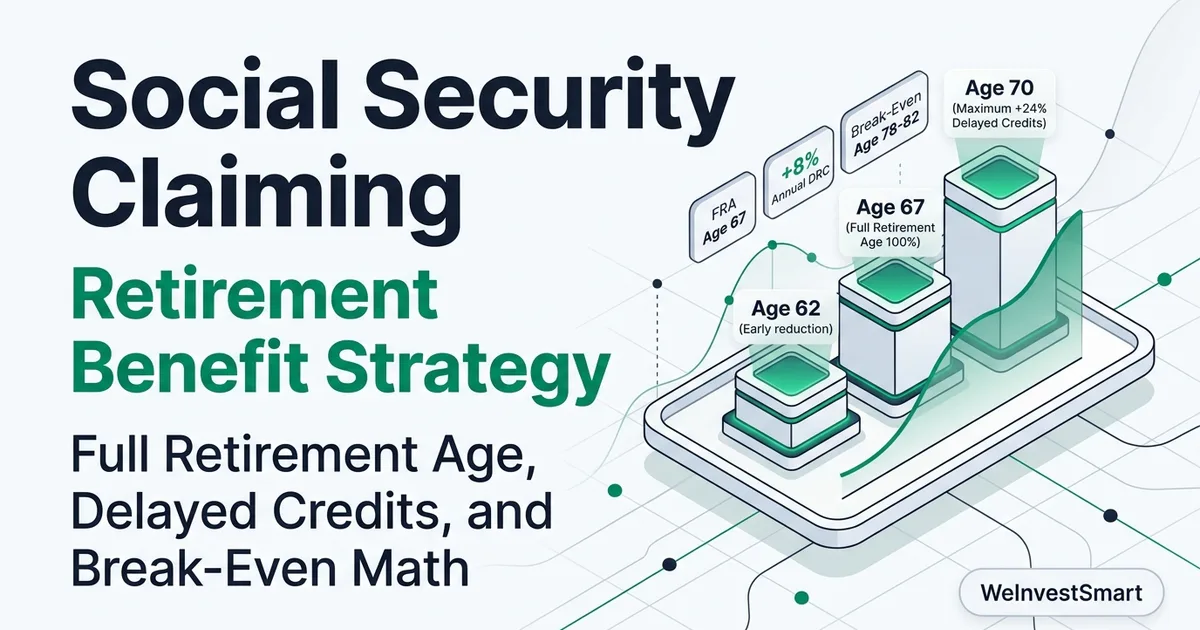
Age 62: $1,400 (70%) • Age 67: $2,000 (100%) • Age 70: $2,480 (124%)- Early Reduction (Age 62-66)
- Full Retirement Base (Age 67)
- Delayed Credits (Age 68-70)
Full Age Claiming Schedule (Ages 62 through 70)
| Claim Age | % of PIA | Monthly Check | Annual Total | Lifetime (to Age 85) |
|---|
If you live to age 85, delaying Social Security to age 70 yields $446,400 in cumulative lifetime benefits, providing $14,400 more than claiming at FRA (67) and $60,000 more than claiming at age 62. Because your expected lifespan exceeds the age 82.5 break-even point, delaying gives you guaranteed longevity insurance.
Last reviewed by the WeInvestSmart Editorial Team · Editorial Policy
On this page
What Is the Social Security Claiming Decision?
The choice of when to claim Social Security retirement benefits is one of the most critical financial determinations an American retiree will ever make. Unlike private pension annuities or commercial life insurance policies, Social Security provides a government-guaranteed, inflation-indexed income stream that cannot be outlived and is backed by the full faith and credit of the United States.
Retirees can initiate benefits at any point between age 62 and age 70. However, the timing of your initial claim permanently establishes your monthly payment multiplier for life under Title II of the Social Security Act. Claiming before your Full Retirement Age (FRA) imposes permanent actuarial reductions, while delaying past FRA earns guaranteed annual increases called Delayed Retirement Credits (DRCs).
The fundamental question is not merely which claiming age yields the largest monthly check, but which age maximizes your cumulative lifetime wealth and protects your household against catastrophic longevity risk.
Good to know: Delayed Retirement Credits cease at age 70. There is zero financial or actuarial benefit to delaying your claim past your 70th birthday. If you have not claimed by age 70, apply immediately to avoid forfeiting retroactive benefits.
To model how Social Security coordinates with private retirement accounts, explore our companion 401(k) calculator, our Roth IRA calculator, and our FIRE early retirement calculator.
How It Works: Actuarial Reductions, Delayed Credits & Break-Even Math
Your monthly retirement benefit is derived from your Primary Insurance Amount (PIA), which represents the monthly benefit you are entitled to receive if you claim at your statutory Full Retirement Age. The Social Security Administration computes your PIA using your highest 35 years of indexed earnings.
Actuarial Multiplier Framework (for Birth Years 1960 and Later, FRA 67)
Under statutory formulas codified in Social Security Program Operations Manual System (POMS) GN 00601:
- Early Claiming Reductions (Ages 62 through 66):
- For the first 36 months claimed prior to FRA: 5/9 of 1% per month (6.67% per year).
- For each additional month prior to FRA (months 37 to 60): 5/12 of 1% per month (5.00% per year).
- Claiming at age 62 (60 months early) results in a cumulative 30% reduction (Multiplier = 0.7000).
- Full Retirement Age (Age 67):
- Entitled to 100% of your PIA (Multiplier = 1.0000).
- Delayed Retirement Credits (Ages 68 through 70):
- For each month delayed beyond FRA up to age 70: 2/3 of 1% per month (8.00% simple per year).
- Claiming at age 70 (36 months delayed) results in a permanent 24% increase (Multiplier = 1.2400).
Monthly Benefit at 62 = PIA × 0.7000
Monthly Benefit at 67 = PIA × 1.0000
Monthly Benefit at 70 = PIA × 1.2400
Cumulative Break-Even Equations
A break-even point occurs at the exact age where the cumulative dollars received from a higher, delayed monthly benefit surpass the cumulative dollars received from starting earlier at a lower payment rate:
Break-Even Age (62 vs. 67) = (Annual Benefit at 67 × 67 - Annual Benefit at 62 × 62) / (Annual Benefit at 67 - Annual Benefit at 62)For someone born in 1960 or later:
- Age 62 vs. Age 67 Break-Even: Exactly Age 78.7 (78 years, 8 months). If you live beyond age 78.7, claiming at FRA 67 yields more total lifetime money than claiming at 62.
- Age 67 vs. Age 70 Break-Even: Exactly Age 82.5 (82 years, 6 months). If you live past age 82.5, delaying to 70 produces superior total lifetime payouts.
- Age 62 vs. Age 70 Break-Even: Exactly Age 80.4 (80 years, 4 months).
Example A illustrates an average earner ($2,000 PIA) living to age 85. Example B illustrates a high earner ($3,200 PIA) living to age 88. Select Try to load either scenario into the calculator above.
Worked examples
| Example A | Example B | |
|---|---|---|
| Primary Insurance Amount (PIA at FRA) | $2,000 | $3,200 |
| Birth Year | 1964 | 1964 |
| Full Retirement Age (FRA) | Age 67 | Age 67 |
| Expected Target Lifespan | Age 85 | Age 88 |
| Monthly Check at Age 62 (70% PIA) | $1,400 | $2,240 |
| Monthly Check at Age 67 (100% PIA) | $2,000 | $3,200 |
| Monthly Check at Age 70 (124% PIA) | $2,480 | $3,968 |
| Lifetime Payout Claiming at 62 (to target) | $386,400 | $698,880 |
| Lifetime Payout Claiming at 67 (to target) | $432,000 | $806,400 |
| Lifetime Payout Claiming at 70 (to target) | $446,400 | $857,088 |
| Break-Even Age (62 vs. 67) | Age 78.7 | Age 78.7 |
| Break-Even Age (67 vs. 70) | Age 82.5 | Age 82.5 |
| Recommended Claiming Age | Age 70 | Age 70 |
| Lifetime Financial Advantage | +$60,000 | +$158,208 |
Key Concepts: Earnings Limits, Taxation & Spousal Coordination
Several statutory rules directly affect how much net income you retain from your Social Security checks:
The Retirement Earnings Test (RET)
If you claim benefits before Full Retirement Age and continue to work as an employee or independent contractor, your benefits are subject to the Retirement Earnings Test:
- Prior to the Year You Reach FRA: The SSA withholds $1 of benefits for every $2 in earned wages above the annual statutory limit ($23,400 in 2025/2026).
- In the Year You Reach FRA: The SSA withholds $1 for every $3 earned above a higher threshold ($62,160 in 2025/2026) up to the month of your birthday.
- After Reaching FRA: The earnings test disappears entirely. You can earn unlimited wages with zero reduction in your monthly benefit.
Crucially, money withheld under the earnings test is not lost. When you attain FRA, the SSA automatically recalculates your benefit upward to credit you for any months where benefits were withheld.
Taxation of Social Security Benefits (IRC § 86)
Social Security benefits may be partially subject to ordinary federal income taxes based on your Combined Income (defined as Adjusted Gross Income + nontaxable interest + 50% of annual Social Security benefits):
| Filing Status | 0% Taxable | Up to 50% Taxable | Up to 85% Taxable |
|---|---|---|---|
| Single / Head of Household | Under $25,000 | $25,000 to $34,000 | Over $34,000 |
| Married Filing Jointly | Under $32,000 | $32,000 to $44,000 | Over $44,000 |
Note: These statutory thresholds were enacted in 1983 and 1993 and are not indexed for inflation. As a result, the majority of middle-class retirees now pay federal income taxes on up to 85% of their Social Security benefits.
How to Use the Calculator: Step-by-Step
Follow this sequential process to identify your personal optimal claiming strategy:
- Obtain Your Official PIA: Log in to your personal my Social Security account and retrieve your estimated monthly benefit at Full Retirement Age.
- Select a Quick Retirement Profile: Choose from our four pre-configured scenarios (Average Earner, Shorter Longevity, High Earner, or Maximum Benefit).
- Set Expected Lifespan: Use your family health history, actuarial life tables, and personal health indicators to enter a realistic life expectancy horizon.
- Evaluate Break-Even Milestones: Review the break-even ages (78.7 for 62 vs. 67, and 82.5 for 67 vs. 70).
- Analyze the Full Age Claiming Schedule: Compare the year-by-year payout grid to see exact monthly checks and cumulative totals for every claiming age from 62 to 70.
Strategic Longevity Protection & Portfolio Drawdown Coordination
For affluent households and individuals with balanced retirement portfolios, delaying Social Security functions as the highest-yielding risk-free investment available in the financial markets:
An 8% Guaranteed Real Return
Where else can an investor earn an 8% simple annual return backed by the United States government? In an economic environment of fluctuating equity markets and modest bond yields, delaying Social Security from age 67 to 70 delivers a guaranteed 24% boost in permanent purchasing power.
Spending Down Pre-Tax Retirement Accounts First
A common wealth-building tactic involves drawing down taxable brokerage accounts or traditional 401(k) / IRA balances between ages 62 and 70 (the “Social Security bridge”). By spending private retirement assets first to delay Social Security, retirees reduce future Required Minimum Distributions (RMDs), generate room for low-bracket Roth conversions, and lock in the maximum possible Social Security benefit at age 70.
To test how paycheck taxes impact pre-retirement savings velocity, utilize our gross-to-net paycheck calculator.
Critical Factors, Survivor Benefits & Early Mortality Risks
While delaying to age 70 is mathematically optimal for those who survive past age 82.5, specific circumstances warrant claiming early:
Watch out: If you are the higher-earning spouse in a marriage, your claiming age determines the survivor benefit for your surviving partner under Section 202(e) of the Social Security Act. Delaying to age 70 locks in the maximum permanent monthly benefit for your spouse if you predecease them.
When Claiming at Age 62 Makes Sense
- Impaired Health & Shortened Life Expectancy: If you have severe chronic medical conditions and do not expect to live past age 78, claiming early maximizes cumulative cash.
- Involuntary Job Loss & Lack of Liquid Assets: If you face involuntary early retirement and lack sufficient savings to bridge the gap to FRA, claiming early prevents high-interest credit card debt or home foreclosure.
- Lower-Earning Spouse Strategy: In married couples where one spouse earned substantially less, the lower earner can claim at age 62 to bring immediate cash flow into the household while the primary earner delays until age 70 to maximize survivor benefits.
Sources and Statutory Authorities
- Social Security Administration: Full Retirement Age Schedule by Birth Year
- Social Security Administration: Delayed Retirement Credits (Title II § 202(w))
- Social Security Administration: Retirement Earnings Test Exempt Amounts
- Internal Revenue Code § 86: Social Security and Tier 1 Railroad Retirement Benefits
- Social Security Act Title II: Federal Old-Age, Survivors, and Disability Insurance Benefits
- Social Security Program Operations Manual System (POMS) GN 00601: Benefit Computations
Frequently Asked Questions About Social Security Claiming Strategy
What is Full Retirement Age (FRA) for Social Security?
Full Retirement Age (FRA) is the statutory age codified in Title II of the Social Security Act at which you are entitled to 100% of your Primary Insurance Amount (PIA). For individuals born in 1960 or later, FRA is exactly age 67. For individuals born between 1943 and 1954, FRA is age 66. For those born between 1955 and 1959, FRA increases by two months for each successive birth year.
How much is my monthly benefit permanently reduced if I claim at age 62?
For retirees with an FRA of 67, claiming at age 62 results in a permanent 30% reduction in your monthly check. The reduction is calculated as 5/9 of 1% per month for the first 36 months early (20%), plus 5/12 of 1% per month for the remaining 24 months (10%), totaling 30%. A $2,000 monthly PIA is reduced to $1,400 per month for life.
How do Delayed Retirement Credits (DRCs) work between FRA and age 70?
Under Section 202(w) of the Social Security Act, for each month you delay claiming benefits beyond your Full Retirement Age up to age 70, you earn an 8% simple annual increase (2/3 of 1% per month). For someone with an FRA of 67, delaying to age 70 permanently boosts your monthly benefit check by 24% over your PIA (increasing a $2,000 benefit to $2,480 per month). Credits cease at age 70.
What is the exact break-even age between claiming at 62 versus waiting until 67?
With an FRA of 67, the nominal break-even age between claiming at 62 (70% of PIA) and claiming at 67 (100% of PIA) is age 78.7 (78 years and 8 months). If you survive past age 78.7, your cumulative lifetime benefit payout from waiting until Full Retirement Age surpasses the total money received from claiming early at 62.
Can I work while receiving Social Security benefits before Full Retirement Age?
Yes, but you are subject to the Retirement Earnings Test (RET). If you are under FRA for the entire year, the IRS and SSA deduct $1 in benefits for every $2 earned above the annual earnings limit ($23,400 in 2025/2026). In the calendar year you reach FRA, $1 is withheld for every $3 earned above a higher limit ($62,160 in 2025/2026). Once you reach FRA, the earnings test vanishes completely, and any withheld benefits are permanently credited back into your monthly check.
Are Social Security retirement benefits subject to federal income tax?
Yes, depending on your Combined Income (Adjusted Gross Income + nontaxable interest + 50% of your annual Social Security benefits). Under IRC Section 86, if Combined Income exceeds $25,000 for single filers ($32,000 for married couples filing jointly), up to 50% of benefits are taxable. If Combined Income exceeds $34,000 for single filers ($44,000 for married couples), up to 85% of benefits are taxable.